



Krishnakumar K T, Chairman and Managing Director of Oleevia Grameen Credits, has called for a shift in lending practices towards evaluating borrowers’ changing financial circumstances rather than relying primarily on historical credit records.
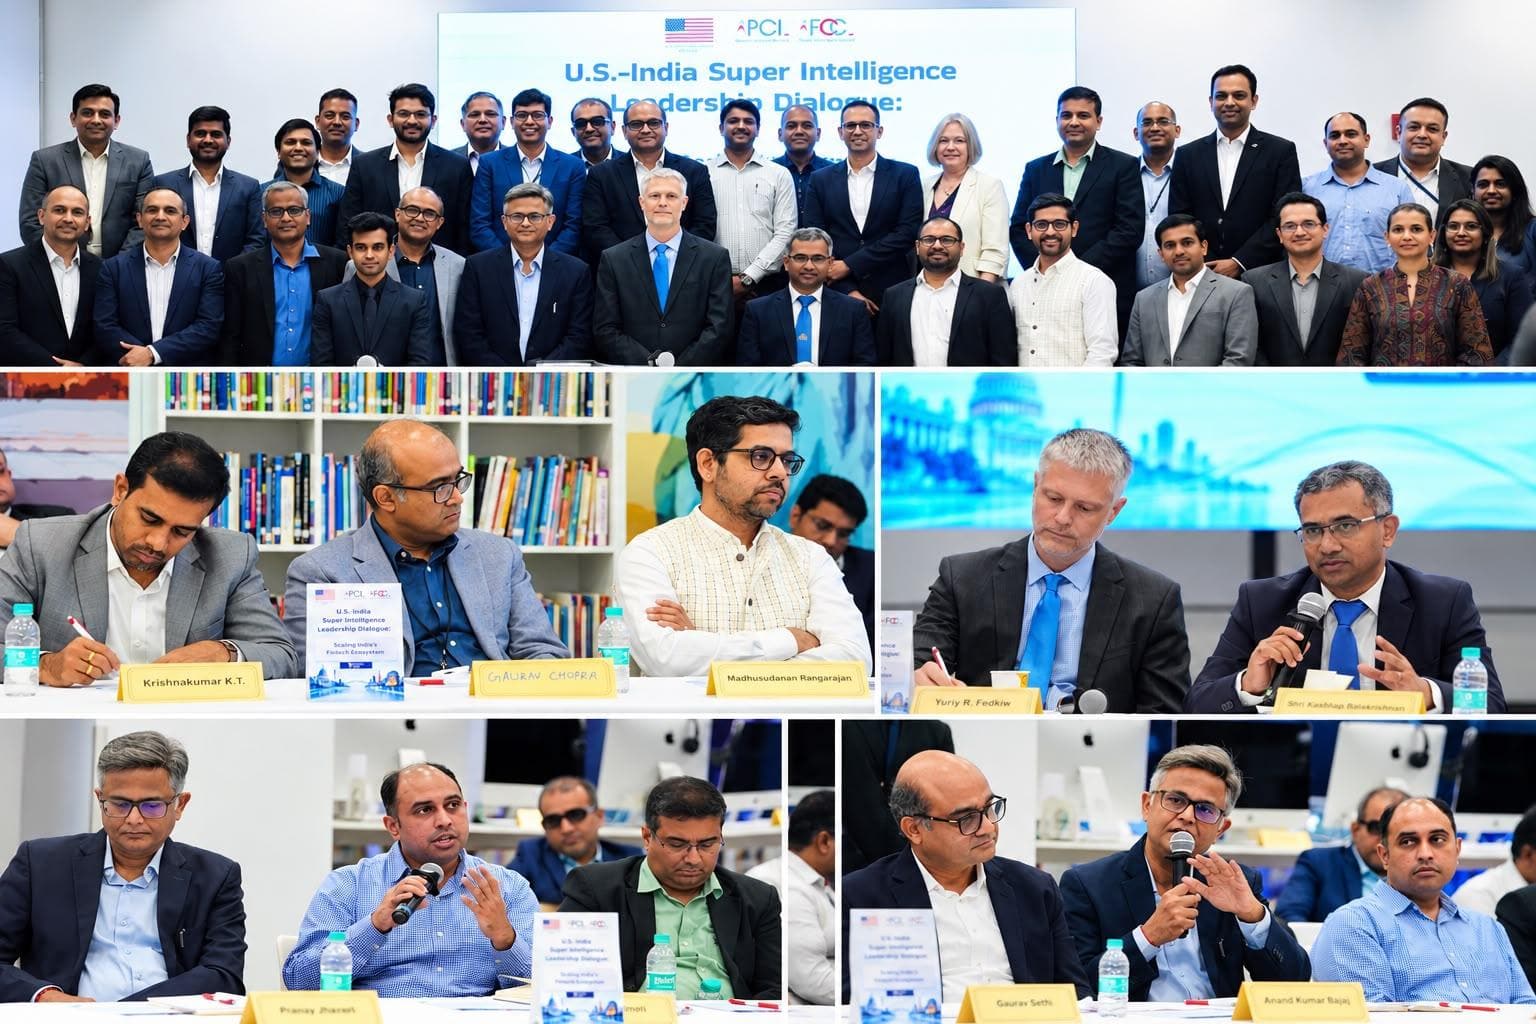
He presented the proposal at the U.S.–India Super Intelligence Leadership Dialogue, held at the U.S. Consulate General in Mumbai. The event brought together representatives from banking, financial services, digital payments and fintech to discuss emerging technologies and opportunities for cooperation between India and the United States.
Organised in collaboration with the Payments Council of India (PCI) and the Fintech Convergence Council (FCC), the dialogue was themed “Scaling India’s Fintech Ecosystem.” Discussions covered artificial intelligence (AI), digital payments, financial inclusion, risk management and emerging intelligence technologies.
Participants included Yuriy R. Fedkiw of the U.S. Consulate General, Kashiap Balakrishnan, Chief General Manager at the Reserve Bank of India, Tapan Malhotra of Google Pay, Anand Kumar Bajaj, CEO of PayNearby, and Vivek Balgavi, Partner at PwC India, among other industry representatives.
Expanding Credit Assessment Beyond Historical Data
Krishnakumar said lenders typically evaluate applicants using credit scores, repayment histories, income patterns, outstanding liabilities and other current financial indicators. While AI has improved data analysis and risk assessment, he argued that lenders should also account for changes in borrowers’ circumstances during the loan tenure.
“Artificial Intelligence is already helping banks understand a borrower’s past and present. The next breakthrough should be Super Intelligence that helps us understand the borrower’s financial future. Financial institutions must be able to anticipate repayment capacity and potential financial difficulties before they become serious problems,” Krishnakumar said.
He proposed combining predictive modelling, cash-flow forecasting, financial behaviour analysis and economic indicators to identify potential risks and support informed lending decisions.
Shifting from Loan Recovery to Borrower Support
Krishnakumar called for banks, non-banking financial companies (NBFCs) and fintech firms to expand customer support after loan disbursement.
He observed that post-disbursement processes often focus on equated monthly instalment (EMI) reminders, overdue notifications, collections and recovery. He argued that lenders should also help customers manage financial difficulties before they result in defaults.
“The purpose of Super Intelligence in financial services should not be limited to improving loan recovery. It should help us identify when a borrower is gradually moving towards financial distress and guide that person towards financial stability before a default occurs,” he stated.
He proposed using legally permissible, consent-based financial information to provide personalised budgeting guidance, cash-flow management, repayment planning, financial counselling and suitable restructuring options where necessary.
Preventing NPAs Through Predictive Intelligence
Reducing non-performing assets (NPAs) was another priority highlighted by Krishnakumar. He said preventing avoidable defaults should complement recovery efforts, benefiting both lending institutions and their customers.
“Instead of developing increasingly sophisticated systems only to recover bad loans, we should develop Super Intelligence systems that help prevent financially responsible borrowers from becoming defaulters. Protecting the financial stability of borrowers is equally important for protecting the financial stability of lending institutions,” he explained.
He identified small businesses, entrepreneurs, self-employed individuals and households as potential beneficiaries of predictive financial tools, particularly when income fluctuations or changing economic conditions affect their ability to meet loan obligations.
Such systems could help lenders improve credit quality and reduce avoidable defaults, provided they use reliable data and operate with appropriate safeguards.
A Four-Stage Framework for Lending
Krishnakumar outlined a framework combining credit assessment with ongoing customer support:
- Past: Review historical credit behaviour and repayment records.
- Present: Assess current income, liabilities and financial capacity.
- Future: Identify potential changes in a borrower's financial circumstances.
- Support: Offer appropriate guidance and assistance based on identified needs.
He called for collaboration among banks, NBFCs, fintech companies and technology providers to develop systems that integrate financial analysis with customer support.
India-U.S. Cooperation in Financial Technology
The dialogue provided a platform for financial sector stakeholders to discuss emerging technologies and their applications. Krishnakumar said responsible innovation, supported by appropriate regulatory safeguards, could help institutions improve lending practices and manage credit risks more effectively.
His proposals focused on broadening credit assessment and complementing conventional recovery processes with technology-enabled borrower support.
About Krishnakumar K T
Krishnakumar K T is the Chairman and Managing Director of Oleevia Grameen Credits, an RBI-registered non-banking financial company headquartered in Thrissur, Kerala.
He has nearly two decades of experience in banking and financial services, including banking product development, lending, financial inclusion, business strategy and financial services management.
He is also associated with entrepreneurial and social development initiatives through the Oleevia Group of Companies, focusing on expanding access to financial services, supporting entrepreneurship and promoting inclusive economic growth.